
What Is Inflation and How Does It Affect Your Money?
Understand how inflation is measured and how it can affect purchasing power, savings, wages and debt.
By TopicWeekPublished 10 min read
In this article
Imagine buying much the same groceries, paying similar bills and using the same services as last year, yet needing more money to cover them. A broad rise in prices over time may be inflation. It does not mean every price rises, or that each household experiences the same change.
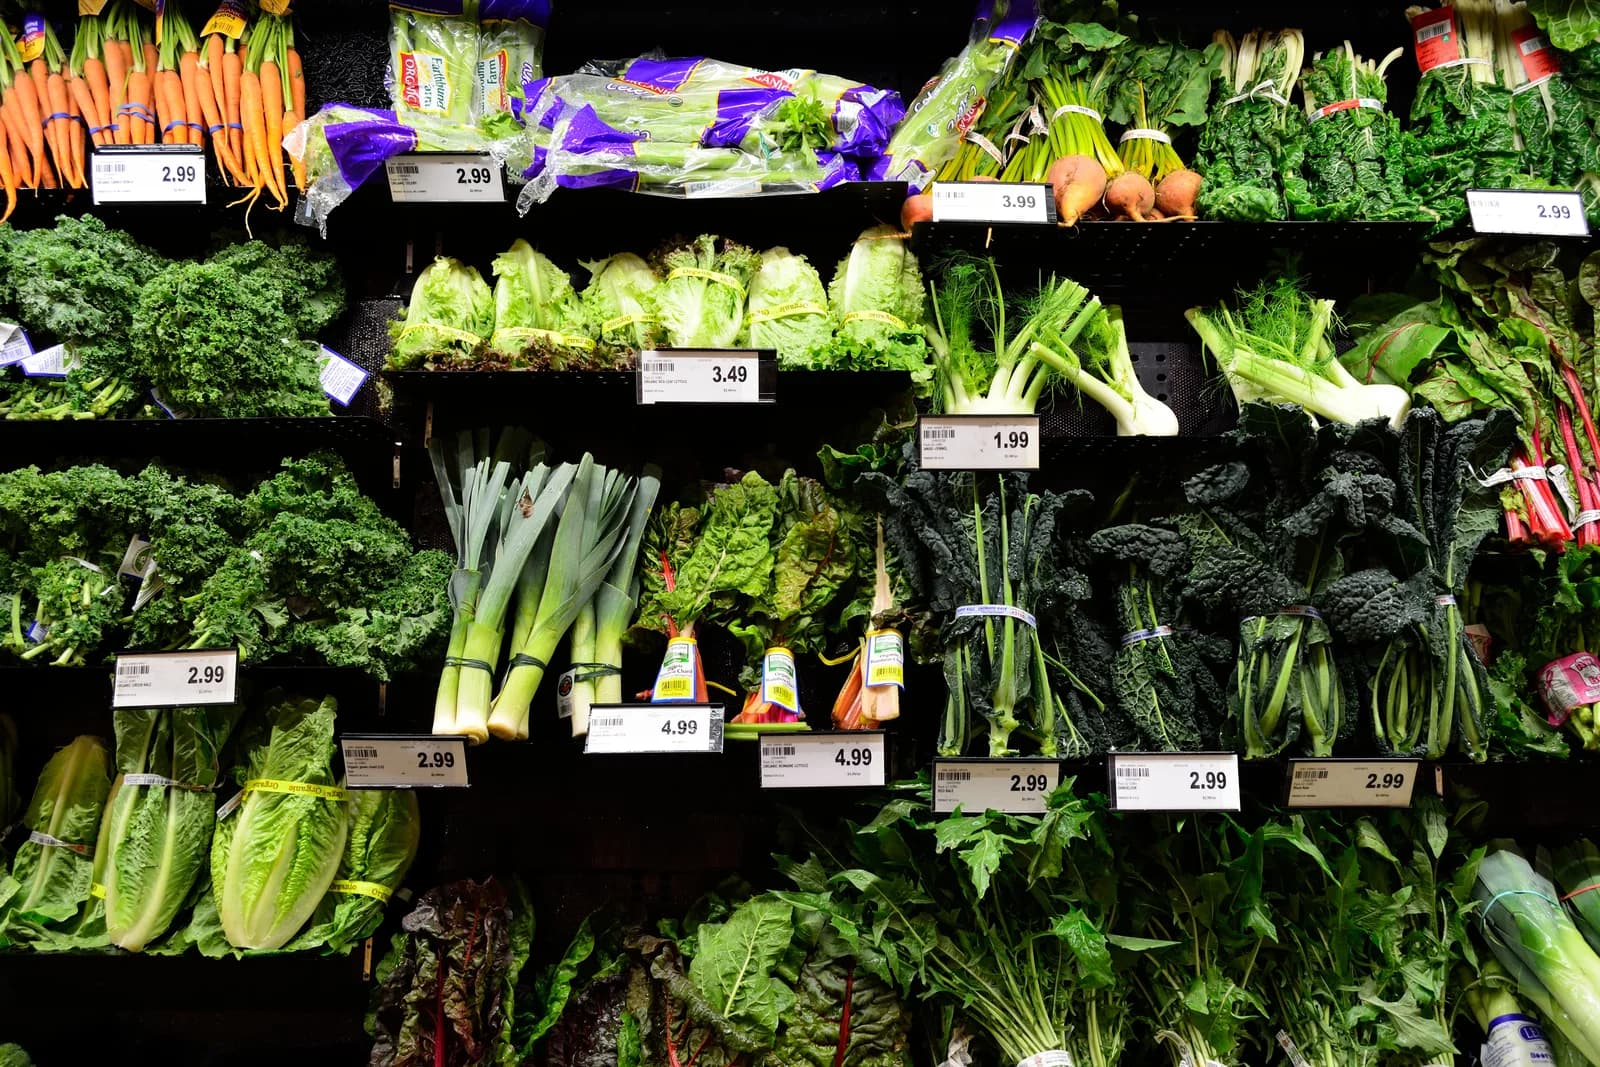
The practical question is not only how many currency units you have, but what they can buy. This guide explains how inflation is measured, why it can happen and how to review your own budget, savings and debts without assuming one strategy works for everyone. All examples are hypothetical and use generic currency units. The supermarket photo is illustrative; the shelf prices shown are not current.
What inflation means
Inflation is a rise in the general level of prices for goods and services over time. It is measured across a collection of purchases, not by checking whether one item became more expensive. Some prices may rise, some may stay similar, and others may fall while the overall index increases. A discount on one product is not deflation.
For example, if a representative basket costs 100 units in one period and 105 in the next, its price has risen by 5%. This describes that basket and those observations; it does not say every item rose by 5%, or that a particular person’s costs changed by exactly 5%.
How inflation is measured
A consumer price index (CPI) tracks prices for a defined set of goods and services bought by households. Statistical agencies estimate spending shares and assign weights: a category taking a larger share of expenditure usually has more influence. The basket, data collection, quality adjustments and update schedule are statistical choices, not a literal list of every household’s purchases.
An index level is often set relative to a reference period, such as 100. It is a comparison scale, not a price tag or the amount every person pays. When checking a published figure, note the country or area, index name, period and whether it is monthly or year-on-year; different indexes should not be treated as interchangeable.
- Monthly change compares an index with the previous month and can be volatile.
- Year-on-year inflation compares the same month with a year earlier; it reduces some seasonal effects but depends on the comparison period.
- A country’s CPI serves its own statistical purposes. Eurostat’s HICP harmonises methods for EU comparisons; it is not identical to every national CPI or a personal cost-of-living measure.
“Core” or underlying inflation helps assess persistent price pressures by excluding some volatile components or applying other statistical methods. There is no single worldwide definition: countries and institutions may exclude different components. One ECB measure excludes energy and food in the euro-area context; that is not a universal rule. Compare the Eurostat HICP methodology, OECD CPI FAQ and the US BLS CPI handbook within their stated scopes.
Why inflation can happen
Inflation can reflect several forces acting together. Their importance changes by time and place; an index describes price movements but does not identify their cause by itself. A shock may begin in one sector and spread through production costs, contracts, wages or expectations. The IMF’s educational overview and BIS research discuss interacting demand and supply factors, not a single explanation. It is therefore misleading to explain every inflation episode only as “printing money”: monetary conditions can matter, but causes and transmission mechanisms interact.
- Demand: spending grows faster than the economy can supply some goods or services.
- Supply disruptions: shortages, transport delays, weather or reduced production limit availability.
- Input costs: energy, raw materials, rent or wages may raise business costs; firms may pass some on, absorb them or change products.
- Imports and exchange rates: a weaker currency can raise some import prices in local money, depending on contracts and markets.
- Expectations and policy conditions: expectations affect price and wage setting. Credit, monetary and fiscal conditions can influence demand and financing over time, but do not directly set each price.
Your own inflation may differ
Purchasing power is the quantity of goods and services a sum can buy. If a basket rises from 100 to 105 units, fixed 100 units buy 100/105 of the old basket: about 0.9524 basket, or 4.76% less purchasing power. The loss is not exactly 5%, because it is the reciprocal of the price increase: 1/1.05 − 1 ≈ −4.76%.
Your personal inflation can differ from the headline rate because people buy different things and face different price changes. A household spending a large share on rent, fuel, care or a particular diet may see a different change from the average basket. The index is useful for broad comparison, not as a bill forecast. An ECB analysis of household-specific inflation explains why experiences vary.
Estimate how your own costs changed
You can make a rough personal comparison without recreating an official index. Choose a representative period and use records you already have. Compare the same recurring expenses or a consistent basket, keeping quantities and product choices in view. The result describes the sample and dates you selected; it is not an official inflation rate or a forecast.
- Choose recurring items or categories and a prior period; use quantities you actually bought.
- Compare like with like. A different brand, package size, quantity or quality can change the bill for reasons other than the price of an identical item.
- Calculate the basket change as (new total / prior total) − 1 and note the dates and items included. One month is not a guarantee of future costs.
What inflation can mean for savings
Inflation does not remove the currency units in an account. It can reduce what those units buy if prices rise faster than the nominal return earned on the account. A simplified real-return calculation is (1 + nominal return)/(1 + inflation) − 1. If savings earn a 3% nominal return before tax and fees while prices rise 5%, 1.03/1.05 − 1 ≈ −1.90% in purchasing-power terms, before taxes, charges and any product risk. This is an illustration, not a forecast.
A sound review separates liquidity (how quickly money is accessible), nominal return, purchasing-power change, fees, taxes, withdrawal rules and risk. Money needed soon may have a different purpose from money for a long-term goal. Comparing only an advertised rate can omit conditions or costs. No account or investment can be assumed to preserve purchasing power in every period.
Inflation, wages and income
A higher salary in currency units is a nominal increase. Compare income growth with the price change over the same period. With a 4% hypothetical pay rise and 5% inflation, the exact real change is (1.04/1.05) − 1 ≈ −0.95%. The shortcut 4% − 5% = −1% is close, but the ratio is exact. Use consistent before-tax or after-tax amounts.
- If pay is unchanged while relevant prices rise, the same income buys less of that basket. If pay rises more slowly than prices, purchasing power falls; at the same rate it is broadly maintained; faster growth raises it. Taxes, benefits, hours and your own spending pattern also affect the outcome.
Inflation and debt
Inflation may reduce the real value of a fixed nominal debt: the amount owed is stated in currency units that may buy less later. That does not make borrowing automatically beneficial. The effect depends on income, whether repayments stay fixed, interest, fees, contract terms and ability to pay. Inflation may raise essential costs before income changes.
Fixed- and variable-rate loans behave differently. A variable rate may change under the contract; central-bank decisions can influence borrowing costs with a lag, but transmission differs by place and product. New borrowers may face different prices and eligibility rules. Read the agreement and compare the full repayment schedule; do not assume past inflation will reduce a future debt burden.
Inflation, disinflation and deflation
- Inflation: the general price level rises. A positive 3% rate means prices are still rising over the comparison period.
- Disinflation: the rate falls but remains positive. A slowdown from 8% to 3% means prices rise more slowly, not that they fall by 5%.
- Deflation: the general price level falls over a period. A discount on one item or a temporary sale alone is not deflation.
Price changes compound. If a hypothetical index rises 5%, then 3%, then 2% in successive years, cumulative inflation is 1.05 × 1.03 × 1.02 − 1 = 10.313%, not 10%. A basket starting at 100 units would cost about 110.31. When an exact cumulative result matters, multiply the period factors instead of adding the rates.
What central banks can do
Many central banks use monetary policy, including policy interest rates, to influence financing conditions and demand. Effects take time and vary by economy. Higher rates may make some borrowing more expensive and moderate spending pressure, while also affecting savings returns, investment, employment and exchange rates. Monetary policy cannot produce energy, repair a supply chain or set every price.
Mandates and targets differ. The ECB, for example, has a medium-term 2% target for the euro area; it is not a rule for every central bank. Fiscal policy, competition, supply capacity and external shocks also matter. The ECB monetary-policy overview explains the euro-area institution’s role; the IMF’s inflation explainer outlines several general mechanisms.
How to review your finances
You cannot choose the inflation rate or control every price, but you can check how your spending and commitments are changing. Start with recent records and compare similar periods. A personal budget can organize the review; it cannot create income or guarantee savings. Protect essential needs and avoid rushed decisions based on a single headline figure.
- Compare actual spending over representative periods; separate essential, flexible and irregular costs.
- Check unit prices, pack sizes, subscriptions and contract renewals; a lower price helps only if the product and conditions still fit.
- Compare income and required payments alongside expenses. If income rises, compare its nominal change with prices over the same period.
- Keep accessible money suited to upcoming bills and plausible emergencies. A reserve provides liquidity, not a guaranteed inflation hedge. See our emergency-fund guide.
- For savings, compare net return, access, fees, taxes, protections and risk. Investments can lose value; there is no universal asset that reliably offsets inflation.
- Review debt terms and affordability, especially if rates can change. If payments are becoming unmanageable, contact a reputable local debt-support service before taking on expensive credit.
Common mistakes
- Assuming every product rose by the headline rate.
- Treating disinflation as a return to earlier prices.
- Adding yearly rates instead of compounding them.
- Calling a nominal pay rise a real gain without comparing the same period.
- Assuming an official average exactly matches a household’s spending.
- Comparing savings returns without checking costs, taxes, access and risk.
A worked household example
Consider a hypothetical household with monthly income of 2,000 currency units and spending of 1,700, leaving 300. Suppose its own comparable basket—not necessarily an official index—costs 5% more after a year while nominal income rises 4%. New income is 2,080 and spending 1,785, leaving 295. Income is 80 units higher in nominal terms, but the monthly margin falls by 5; real income buys about 0.95% less of the comparison basket.
This arithmetic does not predict a real household: some costs may rise more, less or not at all, and taxes, benefits, hours or family needs may change. The useful next step is to identify which actual categories changed and whether adjustments are feasible without harming essential needs. This is an educational illustration, not personal financial advice and not a promise that any action will offset inflation.
Frequently asked questions
- Does inflation mean everything gets more expensive? No. It describes an aggregate rise; individual prices can fall, stay stable or rise at different rates.
- If inflation falls, do prices fall? Not necessarily. A lower positive rate is disinflation: prices still rise, only more slowly.
- How do I know whether my salary gained purchasing power? Compare its nominal change and relevant prices over the same period; use (1 + pay growth)/(1 + inflation) − 1.
- Can inflation reduce the value of savings? It can reduce purchasing power when prices rise faster than net return; the account balance need not fall.
- Why did my shopping bill rise more than official inflation? Your mix and quantity of purchases, location, timing and substitutes may differ from the index basket.
- Does inflation benefit people with debt? A fixed nominal debt may lose real value in some conditions, but rates, income, costs and repayments can offset that.
- Is inflation always harmful? Effects differ by people, contracts and economies. High or unpredictable changes can make planning harder; an average cannot describe every outcome.
- How do I calculate cumulative inflation? Multiply each period’s factor, such as 1.05 × 1.03, then subtract 1. Do not add rates for an exact result.
- How is inflation different from cost of living? Inflation measures prices with a defined index; a household’s cost of living depends on its needs, location, spending and choices.
The key takeaway
Inflation describes how a broad set of prices changes; your finances depend on the prices, income and commitments you actually face. Track purchasing power as well as nominal amounts, compare equivalent periods, and weigh access, costs, risks and personal needs before changing a financial decision. No single index or product removes uncertainty.
Related guides

Money
How to make a personal budget from scratch and keep it on track
Learn to organize available income, fixed and variable expenses, plan periodic bills and review a monthly budget with clear examples.
8 min read

Money
Emergency fund: how much to save, where to keep it and how to start
Learn how to size an emergency fund around essential expenses, build it gradually and choose a place for cash you may need quickly.
9 min read

Money
How to save money every month: realistic methods and common mistakes
Explore realistic ways to review monthly expenses, compare bills, curb impulse buys and build sustainable saving habits without universal promises.
9 min read